As renewable energy capacity continues to grow worldwide, the efficient trading and system integration of solar and wind power become ever more critical. One key element of this shift is the transition from fixed feed-in tariffs (FIT) to feed-in premiums (FIP), which pushes plant operators toward active participation in electricity markets.
For many renewable energy markets, the shift from a fixed feed-in tariff (FIT) to a feed-in premium (FIP) model marks the point at which plant operators must start marketing their own electricity. But what options do plant operators actually have under a FIP regime, and what are the advantages and disadvantages of the market premium model, PPAs, and non-subsidized renewable energy trading?

How does Renewable Energy Trading work?
At a Glance
Definition: What is Renewable Energy Trading?
Renewable energy trading refers to the commercialization of electricity from wind, solar, hydropower, geothermal, and bioenergy assets on power markets, rather than through a fixed feed-in tariff.
Given the variable, weather-dependent nature of renewable generation, the spot market — day-ahead and intraday trading on the power exchange — is the most natural venue: it allows operators to sell power close to actual production, when output (and thus the exact volume available) is already known or forecastable with reasonable accuracy.
Increasingly, however, spot trading is complemented by longer-term products — futures contracts, bilateral over-the-counter (OTC) deals, and power purchase agreements (PPAs) — which allow market participants to lock in prices ahead of delivery and reduce exposure to short-term price volatility. Many investors outsource this entire process to external renewable energy traders and focus instead on developing and operating their assets.
What are the Benefits of Renewable Energy Trading?
Renewable energy trading strengthens the market and system integration of renewable energy through genuine price signals. Given suitable grid and market conditions, this holds especially true when compared with flat feed-in tariffs.
For these reasons, many markets require renewable assets above a certain capacity threshold to move from flat feed-in tariffs to active market trading, with flat tariffs typically remaining available only for smaller assets or those commissioned before a given cutoff date.
That said, operators of older assets are increasingly switching to renewable energy trading as well — whether because their support entitlement, typically capped at a fixed number of years, has expired, or because trading simply looks more lucrative to them.
Who handles Renewables Trading?
In practice, renewable energy trading is usually handled by specialized power trading companies. Only very large energy generators maintain their own in-house departments or dedicated subsidiaries for this. Smaller operators — whether running entire solar and wind farms or individual generation assets — hand this responsibility over to professional traders.
These are power trading houses, large and small, with in-depth knowledge of the power market's opportunities, risks, and sometimes highly granular regulations. The renewable energy trader may not only handle forecasting, sales and settlement, but also the system-critical market roles of Balance Responsible Party (BRP) and dispatcher.
For the plant operator, the renewable energy trader is typically the sole point of contact and business partner on the sales side. Together, they agree on a trading model and a remuneration model. Exactly how the power is ultimately brought to market, however, is usually up to the trader alone — whether they act purely as a trader on the power exchange, or also as an independent supplier to end consumers.
We are your trader and risk manager for renewables and flex assets
Our trading experience and forecasting technology allow us to manage large renewable and flex portfolios at competitive prices.
What Marketing Models exist when trading Renewables?
Renewable energy trading offers several routes to market, each with a distinct risk-return profile. What separates them is less the trading mechanics than the degree of price risk operators retain — and whether that risk is cushioned by a hedge.
Marketing model | Advantages | Disadvantages |
|---|---|---|
Subsidized renewable energy trading | Financial safety net through support schemes during periods of low power prices | Extensive requirements |
Non-subsidized renewable energy trading | Fewer requirements | Risk hedging must be fully self-managed |
PPA (Power Purchase Agreement) | Fewer requirements | Customized risk adjustment can be costly |
Ancillary services | Flexible, supplementary revenue source | Very high technical requirements for the asset |
The Example of Germany: How does the Feed-in Premium (FIP) work in Practice?
The feed-in premium (FIP), also called market premium in Germany, is the delta between the asset's strike price — a reference value guaranteed under the EEG, based on the statutory tariff or the operator's auction bid — and the reference market value, in most cases the monthly market value. The reference market value reflects the volume-weighted average day-ahead price for the respective technology across all hours of the month. The lower market prices are in a given period, the higher the market premium climbs, and vice versa. If the reference price is higher than the asset's own strike price, the market premium drops to zero. In other words: even if the gap between the strike price and the market price turns negative, no negative premium is calculated — instead, "zero support" applies, the defining feature of a one-sided CfD, as introduced above.
Through this mechanism, the market premium makes it easier to operate renewable energy assets profitably in Germany, while still preserving the incentive to achieve high market prices. Thanks to intense competition, this brings a broader economic benefit: average power prices fall. The reasoning is straightforward — the more suppliers feed power into the grid during price peaks, the lower those peaks ultimately turn out to be.
How is the Market Premium calculated?
Strike Price ("Applicable Value") − reference market value = market premium
The reference market value is a figure defined under Annex 1 of the EEG. It reflects the average monthly price that an asset with a standardized feed-in profile would have achieved on the spot market — in other words, a volume-weighted average price. Separate reference market values are determined for solar PV, onshore wind, and offshore wind. For all other EEG-eligible generation types (e.g., biomass, geothermal, and hydropower), the average spot market price across all energy sources applies. The reference market value is published by the transmission system operators after the end of each month and is used exclusively to calculate the market premium as defined under the EEG.
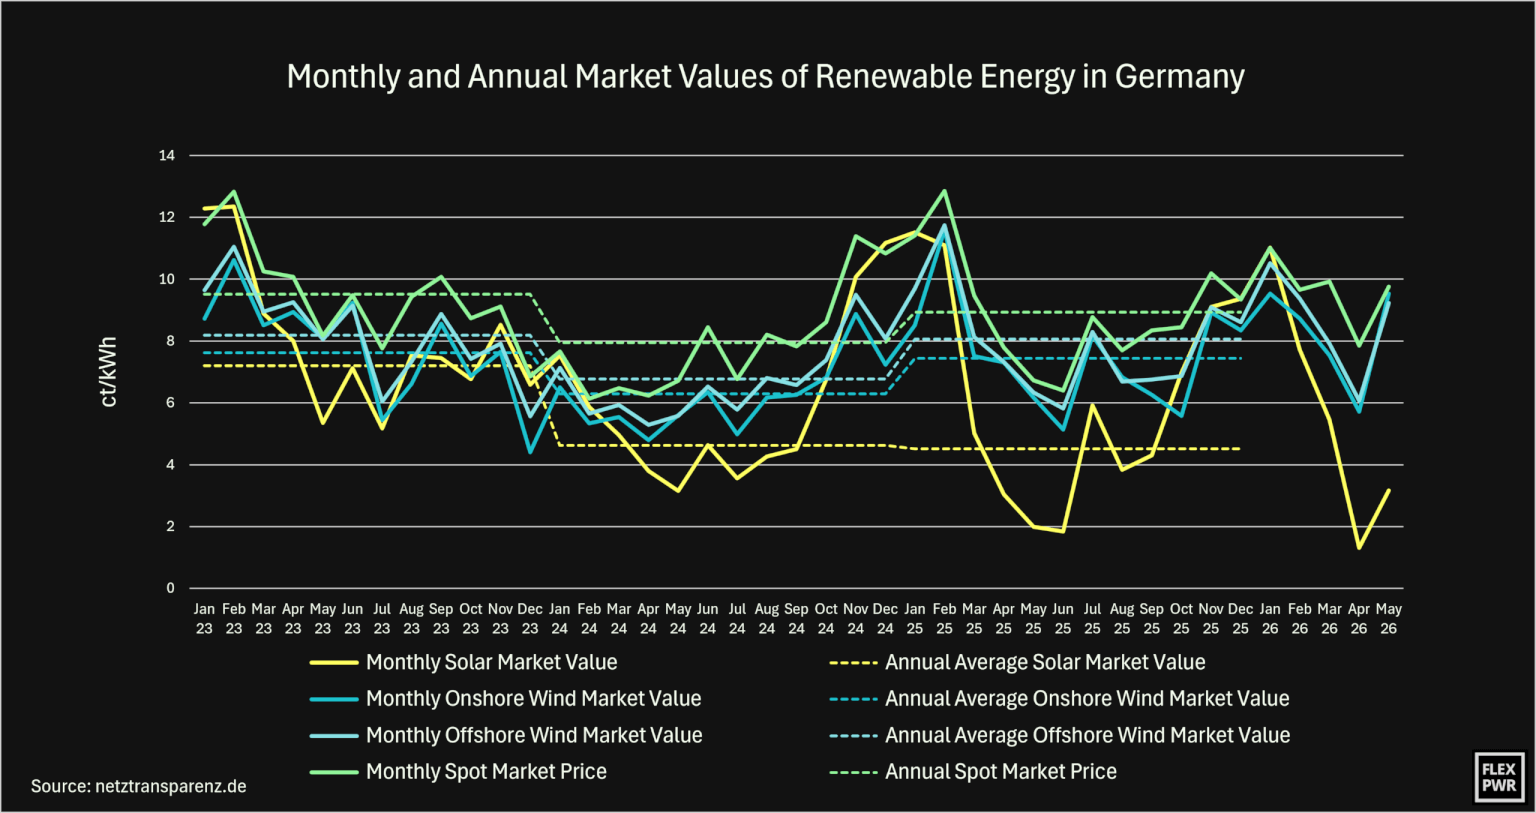
Power prices are lower in summer, an effect that is especially pronounced for solar PV. Here, the higher price partially compensates producers for the lower production volumes.
Unlike the reference market value, the strike price is asset-specific. These days, it's typically determined through reverse auctions as part of government support tenders. In these auctions, plant operators submit bids, which are awarded starting from the lowest until all available capacity is allocated. To improve their chances of winning, operators tend to bid the lowest strike price (in ct/kWh) at which they're willing to commission an asset. In other words, they don't bid the price they actually expect to realize — they've already factored the market premium into their calculation.
The market premium model gives weaker sites a relative advantage ex ante, since they need to bid higher to operate profitably. If awarded a contract, they then receive — per the formula — a somewhat higher market premium than assets at stronger sites that bid lower.
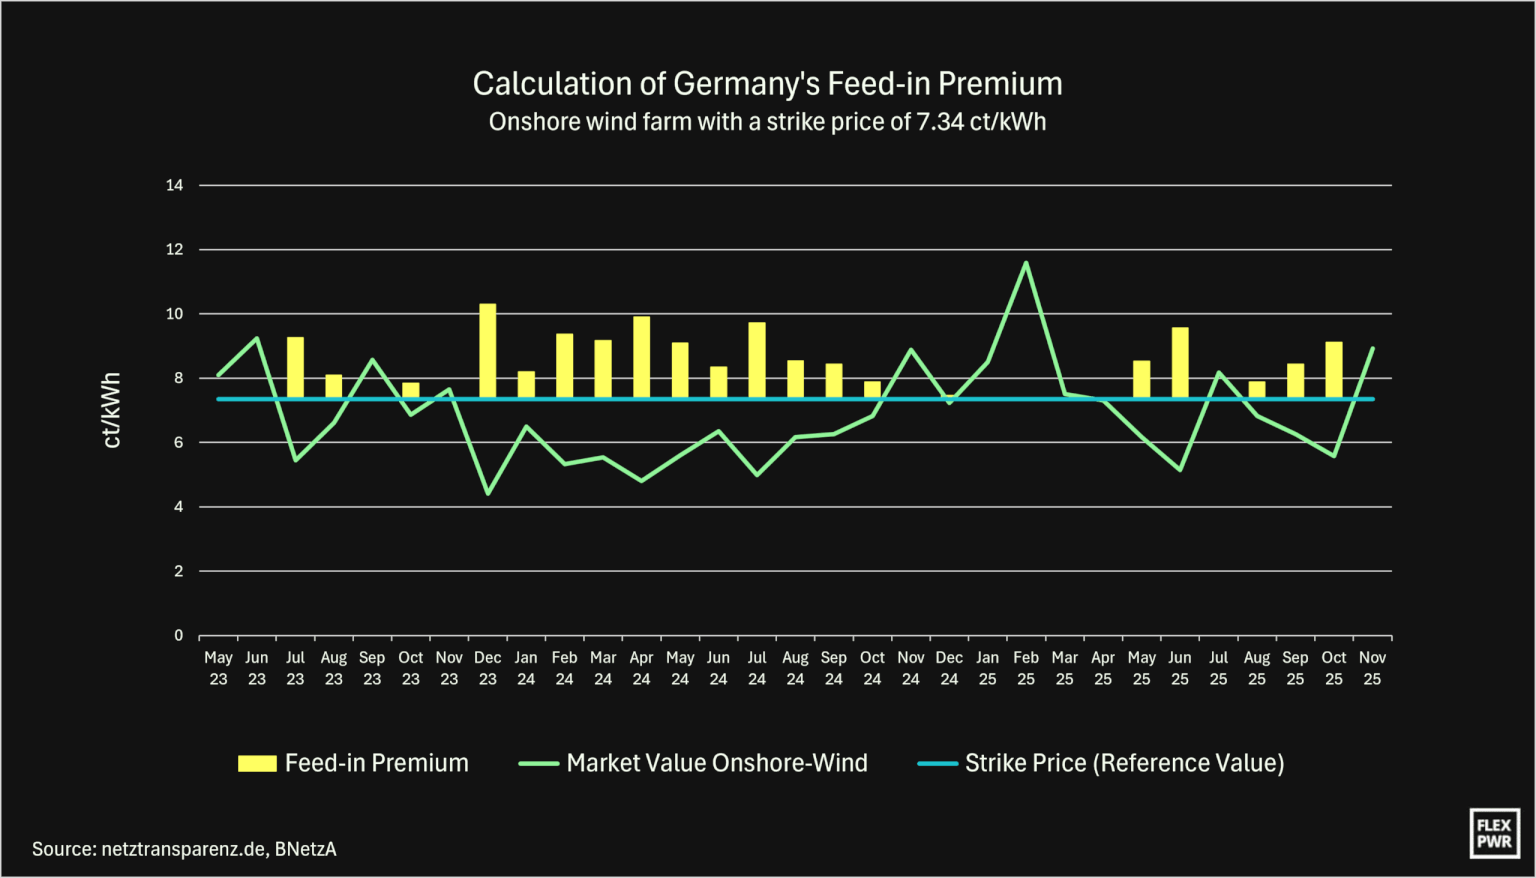
In the onshore wind tender of February 2023, for EEG support starting May 2023, the average applicable value bid was 7.34 ct/kWh. For an asset with this strike price, the market premiums shown here were paid out between May 2023 and December 2025.
Example: Calculating Total Revenue with the Market Premium
An asset's exact revenue depends primarily on actual weather conditions, which determine the timing and volume of power production. Power demand and the trader's skill also play a role.
To sketch out how the market premium works in practice, let's look at an onshore wind asset that won a contract in the February 2023 EEG tender with a strike price of 7.34 ct/kWh — the average bid in that auction. The corresponding market premium (see the previous chart) applied from May 2023 onward.
For this example, we'll assume that the renewable energy trader achieved exactly the average price of all onshore wind assets over the period in question — in other words, the technology-specific reference market value. This gives us:
Total revenue per kilowatt-hour = market price achieved + market premium.
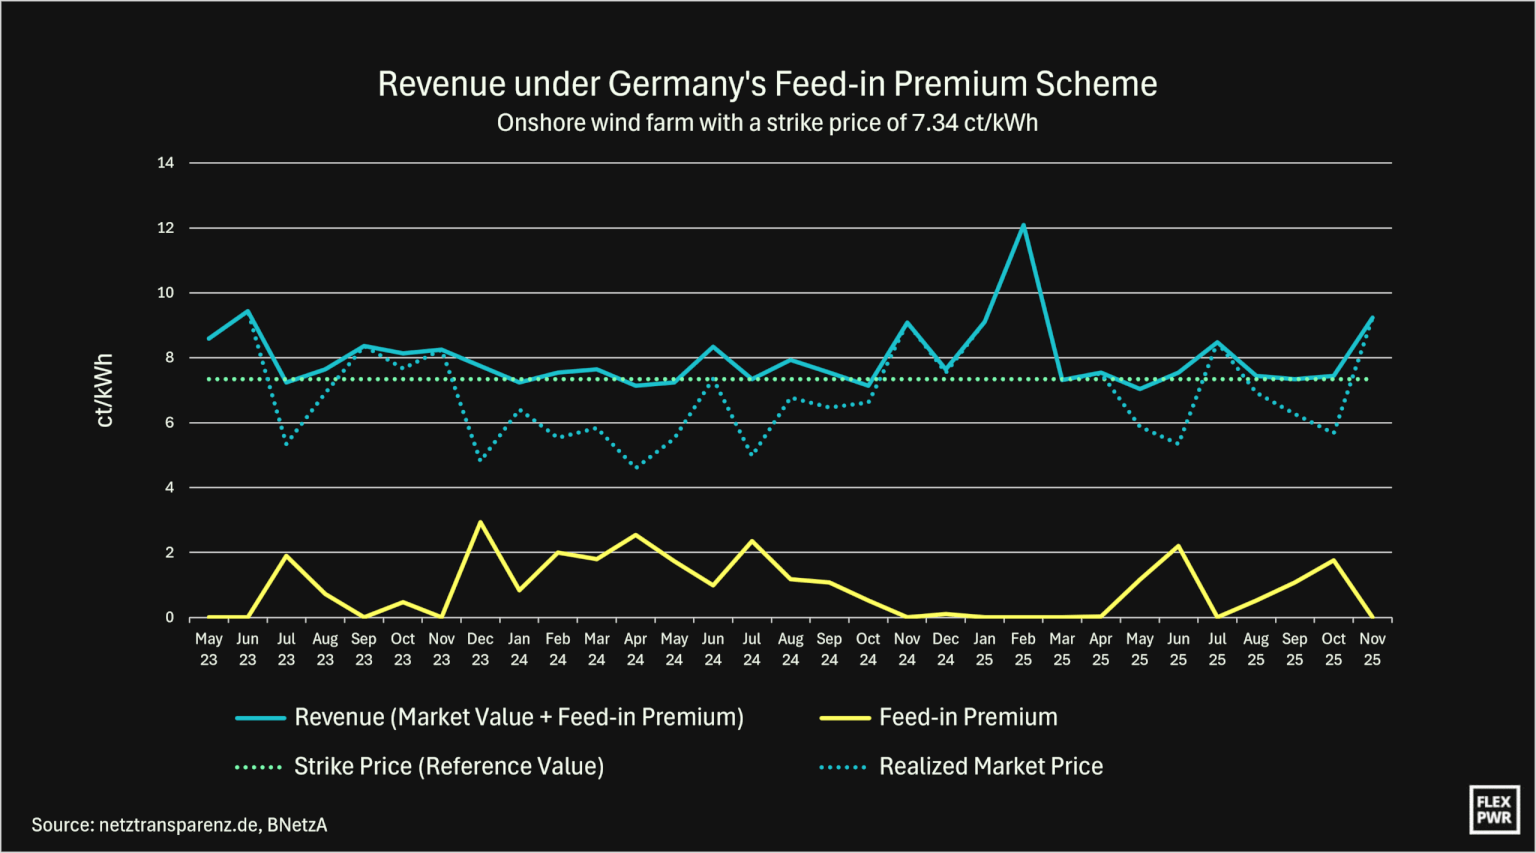
The market premium supports plant operators' revenues especially during periods when market prices are low.
What does "non-subsidized Renewable Energy Trading" mean?
Non-subsidized renewable energy trading refers to selling power without drawing on public support schemes. Revenue then depends entirely on the spot market price, or on individually negotiated contracts.
This model is used, on one hand, for assets that have reached the end of their support period but can still be operated profitably. On the other hand, it also covers new projects that failed to win a support auction, were never registered for one, or lost their eligibility for the feed-in premium because the asset wasn't commissioned in time. Assets lacking the technical capability for remote control by the responsible grid or system operator — a common eligibility requirement under many support schemes — as well as projects already receiving other forms of support, are excluded from the premium regardless.
Some operators, however, forgo public support schemes voluntarily. This has to do with double-marketing bans that a number of support schemes — including Germany's, France's, and Spain's auction system — apply to prevent double compensation: they prohibit issuing a Guarantee of Origin (GoO) for subsidized power. GoOs are certificates that let consumers verify the extent to which they're using sustainably produced power. They carry their own market value, independent of the power price, and can generate additional revenue when traded.
In theory, operators of subsidized assets can often switch between subsidized and non-subsidized trading at defined intervals, depending on the scheme. In practice, however, experience shows that this switch carries certain process risks. As a result, many renewable energy traders prefer longer intervals between switching marketing models.
What are Power Purchase Agreements (PPAs)?
PPAs are long-term power supply contracts between plant operators and offtakers. A distinction is made between physical PPAs, where power is actually delivered, and synthetic or virtual PPAs, which function as a hedging instrument (a contract for difference, or CfD). PPAs offer long-term planning certainty but tend to involve complex contract design — pricing formulas, profile risk, default provisions, and creditworthiness requirements. Increasingly, however, standardized products — also known as Liquid PPAs — are entering the market, bringing greater transparency and lower transaction costs.
In principle, power sold via PPAs often remains eligible for public support. However, this again means no Guarantees of Origin can be issued — something many PPA customers specifically value.
What are Ancillary Services?
Ancillary services are services required to keep the power system stable and secure. Within renewable energy trading, they've so far played only a supplementary — though increasingly important — role. By providing control reserve or other flexibility services, assets under renewable energy trading can generate additional revenue on top of power sales. This further strengthens the market integration of renewable energy, while giving operators an incentive to design their assets to be controllable, forecastable, and grid-friendly. At the same time, it raises the importance of professional dispatch, forecasting, and balancing group management on the part of renewable energy traders.
Renewable Energy Traders are taking on Additional Market Roles
As a result of the implementation of feed-in premium schemes in many countries, renewable energy traders are increasingly taking on responsibilities that were previously handled mainly by power plant operators and grid operators. Today, many renewable energy traders occupy three central market roles in power supply:
The work of renewable energy traders today is far more complex than it was in the early days of the energy transition. Where they once mainly served as service providers to wind and solar asset operators, they now carry out functions that are critical to the system as a whole.
Frequently Asked Questions on Renewable Energy Trading
Traders acting as balancing responsible parties (BRPs) are typically accountable to the transmission system operator (TSO) for scheduling — or nominating — the output of the assets in their portfolio. This means they must produce accurate feed-in forecasts, which for solar and wind are driven above all by weather conditions, in order to avoid imbalance penalties. As a result, weather forecasts are hugely important for renewable energy trading — even though asset operators themselves are rarely confronted with this directly, since they typically bear no risk for forecast deviations.
In many markets, this is typically agreed clearly upfront: renewable energy traders charge a fixed fee per megawatt-hour (MWh) of marketed power.
This fee typically covers more than the direct costs of trading itself — staff, exchange membership, and collateral requirements, for example. It also compensates traders for the risks they take on, such as the forecasting risk described above. Since traders are usually the ones financially exposed to deviations between forecast and actual feed-in, the fee needs to reflect that risk as well.
The risk profile differs significantly depending on which marketing model is used. Under the feed-in premium (FIP), traders — as balancing responsible parties — carry the imbalance risk described above: if actual feed-in deviates from the forecast used for nomination, this triggers imbalance penalties. Price risk, meanwhile, is only partially retained, since the support scheme cushions against low market prices, at least up to the asset's strike price.
Non-subsidized trading removes that cushion entirely. On top of the same imbalance risk, operators and their traders are now also fully exposed to spot price risk — with no floor from a support scheme, the entire revenue is at the mercy of market prices in the relevant delivery period.
PPAs shift the risk picture again. By fixing a price for part of the output in advance, they reduce short-term spot price risk — but introduce counterparty risk: the buyer's ability and willingness to honor the contract over its full term, which can run for many years. Other risks specific to PPAs include volume risk, if actual generation deviates from the contracted volume.
The capture rate measures how much of the average market price a wind or solar asset actually manages to "capture" through its generation, compared to the average day-ahead price over the same period. A capture rate of 100% would mean an asset earns exactly the average price; below 100% means it earns less.
For wind and solar, capture rates are structurally low — and tend to fall further as more renewable capacity is added to the grid. The reason lies in the merit order: solar and wind assets in the same region tend to generate at the same time, whenever the sun shines or the wind blows. This drives up supply exactly when many similar assets are feeding in simultaneously, pushing prices down at precisely those hours — including into negative territory during periods of oversupply. As a result, wind and solar assets systematically earn less than the average market price, since their output is concentrated in the hours when prices are depressed by their own (and their peers') generation.
This effect is often referred to as self-cannibalization: the more wind and solar capacity is added, the more these technologies undercut their own achievable price, since they all tend to produce — and therefore compete for market share — at the same times.
Yes — despite falling into the same broad category of variable renewables, solar and wind pose quite different challenges for trading.
Ramp behavior differs significantly: solar output follows a predictable daily curve, rising and falling with sunrise and sunset, and can ramp up or down sharply within minutes as clouds pass. Wind, by contrast, can change more gradually but also more unpredictably, driven by weather systems that shift over hours rather than minutes — and can produce sudden, large swings during storm fronts.
Seasonality also plays out differently: solar generation is highly concentrated in summer months and daylight hours, while wind tends to be stronger in autumn and winter, and can generate around the clock. This gives the two technologies a complementary, though not perfectly offsetting, seasonal profile.
These differences translate directly into forecasting difficulty: wind forecasts, in particular, tend to carry more uncertainty than solar forecasts, especially over longer horizons — solar's diurnal pattern is comparatively easier to predict, at least on days without volatile cloud cover.
Forecasting complexity is therefore one of several factors that can influence how renewable energy traders set their fees for different technologies.
From Action to Zuccess
Knowledge is Key
Achieving 100% Renewable Energy is a generational task which requires innovation and knowledge on an unprecedented level. We will get faster to 100% Renewable Energy when we as a generation share as much information as possible with each other. This is what we strive for with our School of Flex.
Flex Index
"How much money can I make with a battery?", we get asked a lot. To answer this question, we created the Flex Index, which is a transparent reference for the value of flexibility on the German power market. Check it out...
Videos & Podcasts
Nothing beats first-hand knowledge from experts. Our energy traders and engineers give insights into their job, the market environment they operate in, and what we are working on.
Speaker wanted?
You are on the hunt for a speaker on topics such as power trading, battery energy storage, or the need to balance renewables?
Ask for a speaker and we will send one of our experts to your lecture or conference.
Do you have it in you to be an energy trader?
Find out by taking the ultimate power trader's quiz and answer questions on energy markets and trading strategies!
Discover our Services
FLEXPOWER helps you to bring your portfolio to the energy market. We combine over 25 years of experience in renewables trading in our seasoned team of short-term energy traders. We manage large-scale renewable portfolios and flexible assets with our lean and fully digitized approach.
Say Hi!
Citadel FlexPower GmbH
Citadel FlexPower GmbH (formerly CFP FlexPower GmbH)
Lippmannstraße 8
22769 Hamburg
Tel: +49 40 60778-6155
© 2026 Citadel FlexPower GmbH
(formerly CFP FlexPower GmbH)